Al Barakah Investments Group
Managing Director's Market Intelligence Report
UAE & UK Investment Outlook — H2 2026 & 2027 Strategic Guidance
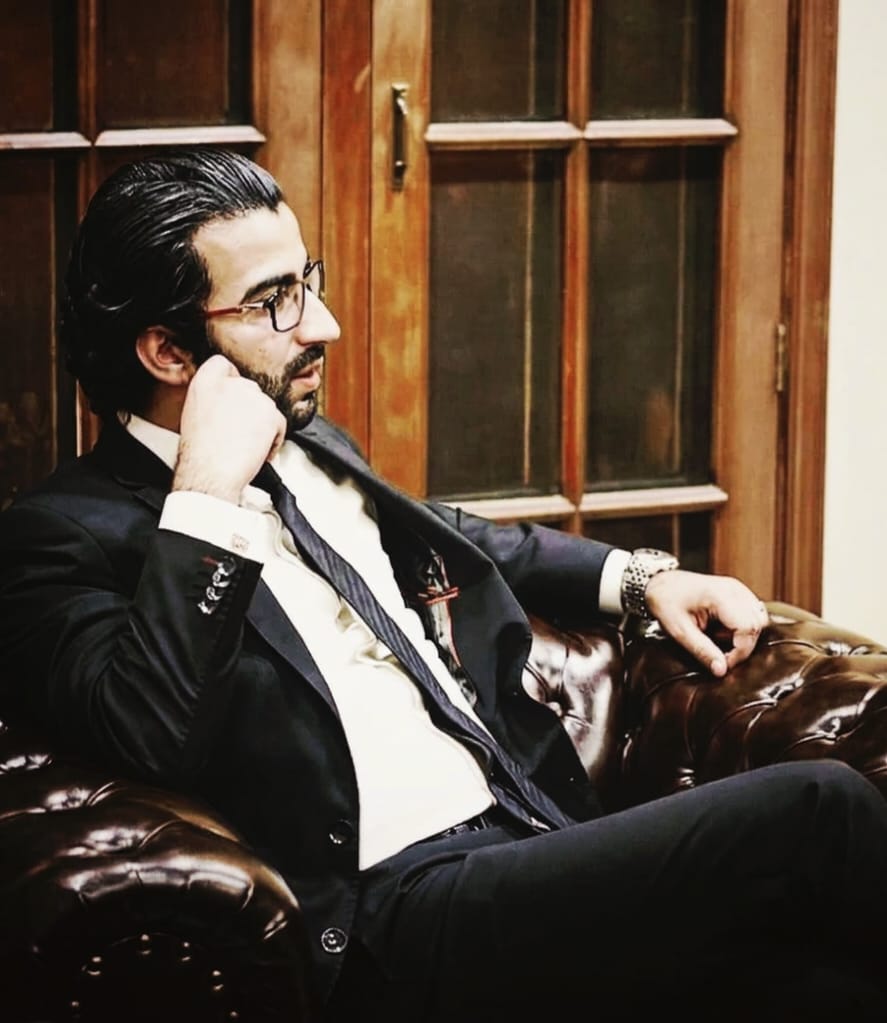
Mr. Faaris Awan
Managing Director — Al Barakah Investments Group
"The window of opportunity in both the UAE and UK markets is open — but it requires precision, patience, and the right partner."
Dear Valued Investor, as we navigate H2 2026 and look ahead to 2027, the global investment landscape is presenting both remarkable opportunities and elevated risks. At Al Barakah Investments Group, our 28 years of cross-market expertise and our unwavering commitment to Shariah-compliant investment structures place us in a unique position to guide you through what is shaping up to be one of the most consequential investment periods of the decade.
Dubai's real estate sector has recorded 118,000 residential transactions worth AED 412 billion in H1 2026 alone — up 14% in value year-on-year. Simultaneously, the UK market is presenting a strategic entry point, with Knight Frank forecasting accelerating price growth of 3–4% through 2027–2028. The data is clear: the informed investor who acts now, in the right asset classes, in the right locations, stands to generate significant halal returns.
Below is my personal analysis — backed by live DLD data, CBRE UK research, and Knight Frank forecasts — to help you make informed decisions. I encourage you to study it carefully and reach out to our advisory team to build a bespoke strategy aligned with your goals.
Mr. Faaris Awan
Managing Director, Al Barakah Investments Group
June 2026
Live Market Data
Key Indicators — Q2 2026
4.4%
UAE GDP Growth
IMF 2026
118K
Dubai H1 Transactions
+9% YoY
AED 412B
DLD Transaction Value
+14% YoY
7.5%
Dubai Avg Villa Yield
Zero tax
3–4%
UK Price Growth 2027F
Knight Frank
4.15%
CBUAE Base Rate
Post-June cut
Market Analysis
UAE — Dubai Real Estate 2026/2027
Dubai's property market is maturing from a speculative cycle into a structurally-driven growth phase. With a population surpassing 4 million, an IMF-forecast UAE GDP growth of 4.4%, and Al Maktoum Airport's Phase 1 operations launching in 2027, the fundamental demand drivers remain exceptionally strong. Villas are outperforming apartments (+10.8% vs +6.3% YoY) due to supply constraints, while rental yields across key communities remain 3–5x higher than equivalent London assets — with zero property tax and zero capital gains tax.
| Area | YTD Growth | Gross Yield | Strategy Tag | Risk |
|---|---|---|---|---|
| Dubai Hills Estate | +12% YTD | 5.6–6.4% | Capital Growth | Low-Med |
| Creek Harbour | +11% YTD | 5.8–6.8% | Waterfront Premium | Low-Med |
| MBR City | +13% YTD | 6.2–7.2% | Infrastructure Play | Medium |
| JVC | +9% YTD | 7.5–8.5% | High Yield | Low |
| Dubai South | +14% YTD | 8.0–8.8% | Airport Corridor | Medium |
Source: DLD Q2 2026, RERA rental contracts, Sikandar Analytics
Market Analysis
UK — Property Market 2026/2027
The UK residential market is entering an accelerating growth phase. Knight Frank forecasts 1.5% price growth for 2026, rising to 3% in 2027 and 4% in 2028 — making 2026 an optimal accumulation window before the curve steepens. Consumer sentiment has strengthened, inflation continues declining, and the Bank of England's rate trajectory is supportive. For international investors, the combination of sterling-denominated assets, strong rental demand in regional cities, and HS2 infrastructure tailwinds creates a compelling risk-adjusted case.
| Location | 2026 Forecast | Gross Yield | Strategy Tag | Risk |
|---|---|---|---|---|
| Prime Central London | +2.5% 2026F | 3.2–4.0% | Wealth Preservation | Low |
| Manchester City Centre | +4.1% 2026F | 5.5–6.5% | High Yield North | Low-Med |
| Birmingham Digbeth | +5.2% 2026F | 5.8–7.0% | HS2 Corridor | Medium |
| London Zone 2–3 | +3.0% 2026F | 3.8–5.0% | Rental Demand | Low |
| Leeds City Centre | +4.8% 2026F | 6.0–7.2% | Growing Tech Hub | Low-Med |
Source: Knight Frank Q2 2026, CBRE UK Market Outlook 2026, Aberdeen Investments Q2 2026
Comparative Analysis
Dubai vs Global Markets — Net Return Edge
Dubai (JVC)
7.5%
Gross Yield
Dubai (Business Bay)
6.5%
Gross Yield
London (Zone 2)
3.2%
Gross Yield
New York (Manhattan)
2.8%
Gross Yield
Singapore
3.5%
Gross Yield
MD's Recommendations
What Should Investors Do in 2026–2027?
Dubai Off-Plan — Buy Selectively
Focus on Tier 1 developers (Emaar, DAMAC) in established corridors. Al Maktoum Airport expansion and Metro Blue Line delivery in 2027 underpin long-term capital appreciation of 8–14% YTD in target areas.
UK Residential — Strategic Acquisitions
With Knight Frank forecasting 3% price growth in 2027 and 4% in 2028, 2026 presents an optimal entry window. Focus on Manchester, Birmingham, and Leeds for superior yield (5.5–7%) ahead of HS2 infrastructure delivery.
Portfolio Diversification Across Both Markets
A split allocation — 60% UAE (high yield, zero tax) and 40% UK (stability, sterling appreciation) — provides a Shariah-compliant dual-market hedge. AED-USD peg eliminates currency risk on UAE holdings.
Avoid Speculative Off-Plan Flipping
Elevated flipping volumes in Dubai South and sub-AED 1.5M tickets signal speculative heat. We advise holding 3–5 year minimum to capture infrastructure-linked capital appreciation while avoiding short-term volatility.
Key Risk Factors to Monitor
Off-Plan Speculation
WatchSub-AED 1.5M flipping elevated in Dubai South & MBR City
UAE Supply Pipeline
Moderate52,000 units forecast H2 2026 — absorption at 84%
UK Mortgage Rates
ImprovingBank of England rate trajectory supportive for 2027 entry
Geopolitical
StableUAE neutrality & HNW migration net-positive in 2026
A Message from the MD
"Al Barakah has been building wealth for families across three continents for 28 years. We do not chase trends — we study markets, structure halal opportunities, and walk with our clients every step of the way. The data for 2026–2027 is compelling. Let us build your strategy together."
Mr. Faaris Awan
Managing Director, Al Barakah Investments Group
This report is prepared by Al Barakah Investments Group for informational purposes only. Data sourced from DLD, Knight Frank, CBRE, IMF, and Aberdeen Investments Q2 2026.